
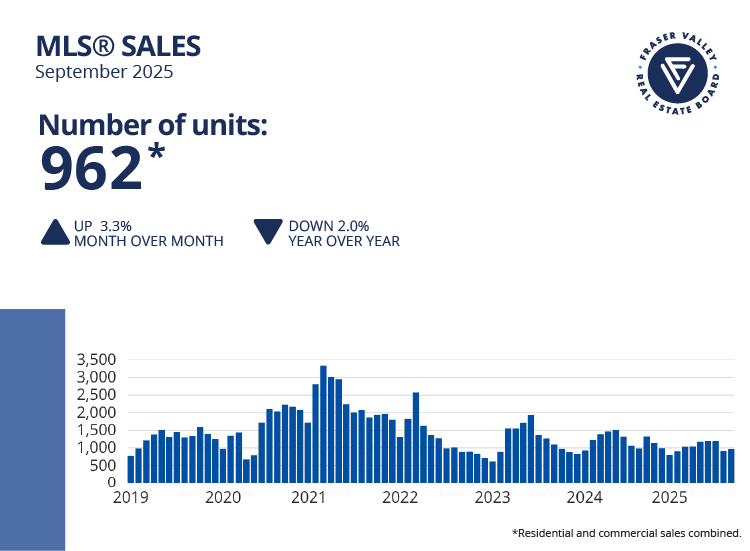
September showed a small uptick in activity after a very quiet August, but the market remains soft. Sales came in at 962, up 3% from August, but still 2% below last September and about 28% under the 10-year average.
Inventory remains high. Active listings reached 10,583, up 1% from August and up 17% from last year. New listings jumped 23% from August to 3,447 as sellers re-entered the market for fall. With high supply and modest demand, the sales-to-active listings ratio sits at 9%. The Board defines a balanced market between 12 and 20%, so we are still firmly in buyer’s territory.
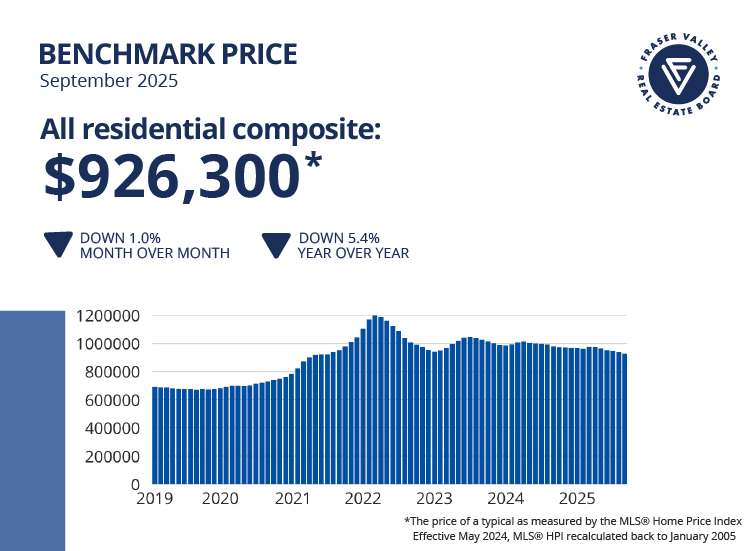
Prices continued to ease. The composite benchmark price dropped 1% in September to $926,300, now down 5.4% year over year.
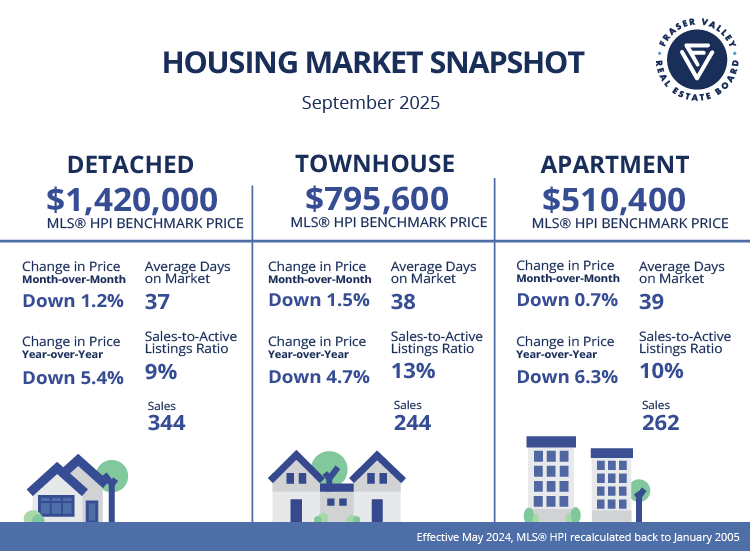
Detached homes fell to $1,420,000, down 1.2% from August and 5.4% from last September. Townhomes dropped to $795,600, down 1.5% month over month and 4.7% annually. Condos slid to $510,400, down 0.7% from August and 6.3% from last year.
Days on market reflect the same story. In September the average time to sell was 37 days for detached, 38 for townhomes and 39 for condos. Compared to August, detached homes increased slightly from 38 days, townhomes rose from 32, and condos decreased from 41.
Median days show a more nuanced picture. Detached held steady at 27 days, condos ticked up to 27 from 26, but townhomes improved sharply to 18 days from 23. Townhomes are clearly the bright spot right now.
Families who can’t make the jump to detached are choosing townhomes for more space at a lower cost, and that is driving faster absorption in that segment.
On the ground, showings have picked up slightly compared to August and a few more offers are being written. But price is still the sticking point. Buyers and sellers remain far apart on expectations, and the increase in failed listings shows many homes are still being withdrawn and repositioned.
While I have noticed more activity on sluggish listings, it’s from a combination of aggressive price reductions on Seller’s parts, rather than simply renewed Buyer attention.
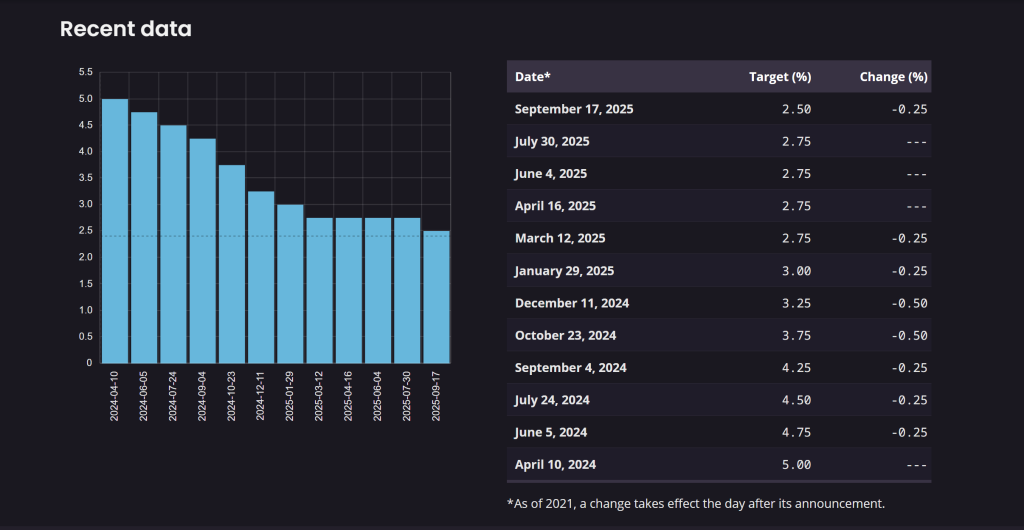
In monetary policy, the Bank of Canada cut its overnight rate by 25 basis points on September 17, bringing it to 2.50%. That was the third rate cut this year, following earlier reductions from 3.00% in January to 2.75%, and then to 2.50%.
That cut was driven by weakening economic data and a softening labour market.
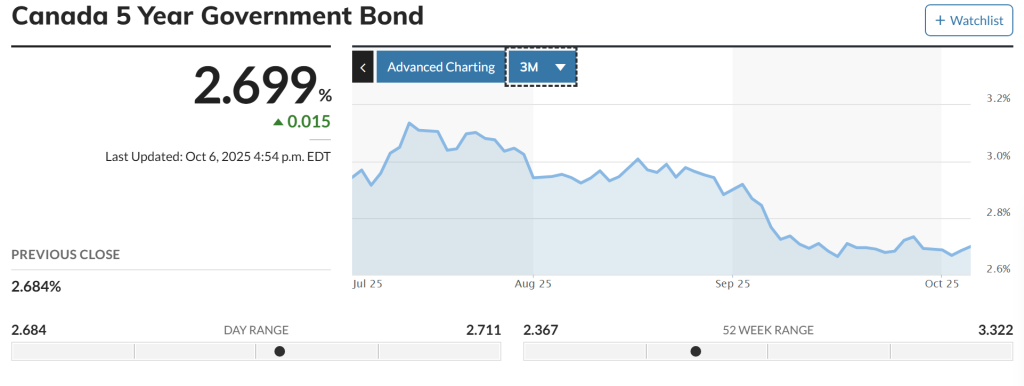
Bond yields have only softened slightly, which limits relief for fixed mortgage rates.
From an economic perspective, consumer confidence remains low as households continue to grapple with elevated costs and limited wage growth. Several sectors are reporting layoffs, particularly in construction, manufacturing, and tech.
While unemployment is not spiking dramatically, Statistics Canada notes that job vacancies have declined sharply, which points to a softer employment outlook heading into winter.
Meanwhile, delinquencies are rising gradually across both mortgage and non-mortgage debt. It is not panic-worthy yet, but it does add another layer of caution for would-be buyers.
Fall usually brings a stronger bump in activity, but so far this year it looks muted. We have more showings and a few more offers, but prices are still slipping and high inventory keeps buyers in control.
If you are buying, this is a market of choice and negotiation power. If you are selling, you need to price realistically and stand out from the competition.
And if you would like a breakdown of the numbers in your specific neighbourhood or property type, check out the market areas page or reach out to me directly. Whether you are planning a move now or just want to explore your options, I am happy to help.


