
Fraser Valley Market Shows Early Bloom With February Sales Lift – But It Is Still Too Early to Celebrate
The Fraser Valley market showed the first hints of spring activity in February, with sales increasing from January. However, the overall picture remains subdued compared with typical seasonal levels.
Sales Increase From January But Remain Well Below Seasonal Norms
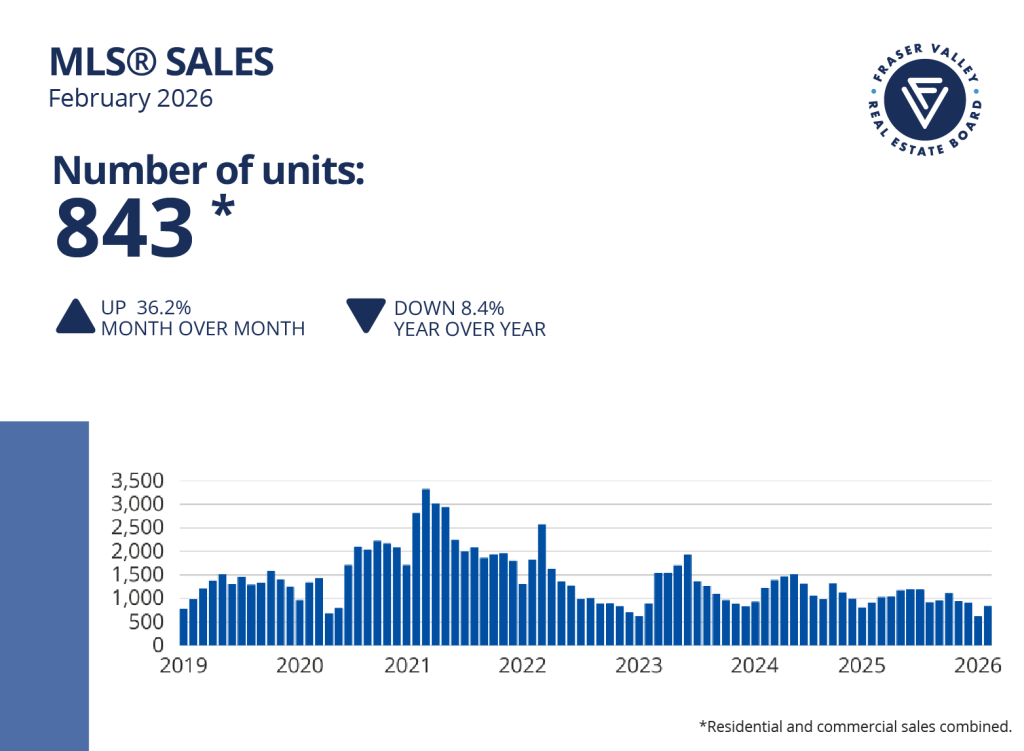
The Fraser Valley Real Estate Board recorded 843 sales in February.
That represents:
- 36% increase from January
- 38% below the ten year seasonal average
So while activity improved from the slowest month of the year, it remains well below what we would normally expect heading into spring.
New listings actually declined slightly in February, falling 9% to 2,796 listings. Some sellers appear to be waiting for the traditional spring surge before bringing their homes to market.
Inventory remains elevated.
Active listings rose to 8,344 homes, up 8% from January and sitting 51% above the ten year seasonal average.
With supply still outpacing demand, the sales to active listings ratio currently sits at 10%.
A balanced market is generally considered to fall between 12% and 20%, which means the Fraser Valley remains firmly in buyer’s market territory.
Fraser Valley Home Prices Continue Gradual Decline
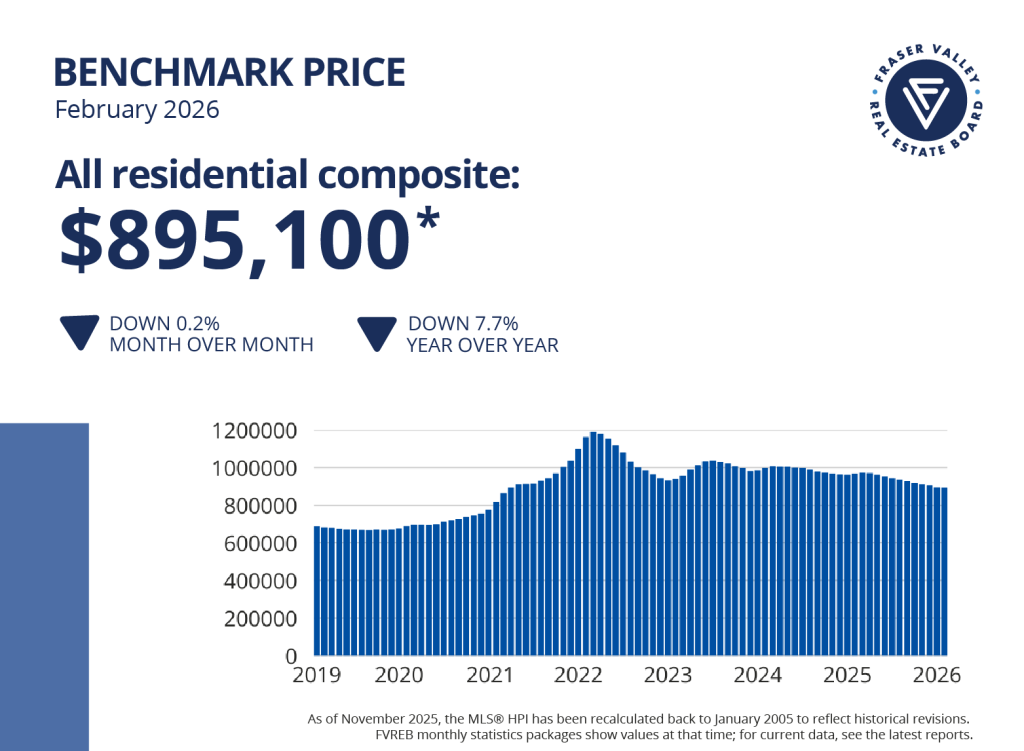
Prices continued to edge lower in February.
The composite benchmark price declined 0.2% to $895,100, continuing the gradual downward trend that has been developing over the past year.
Price Trends by Property Type
Detached Homes
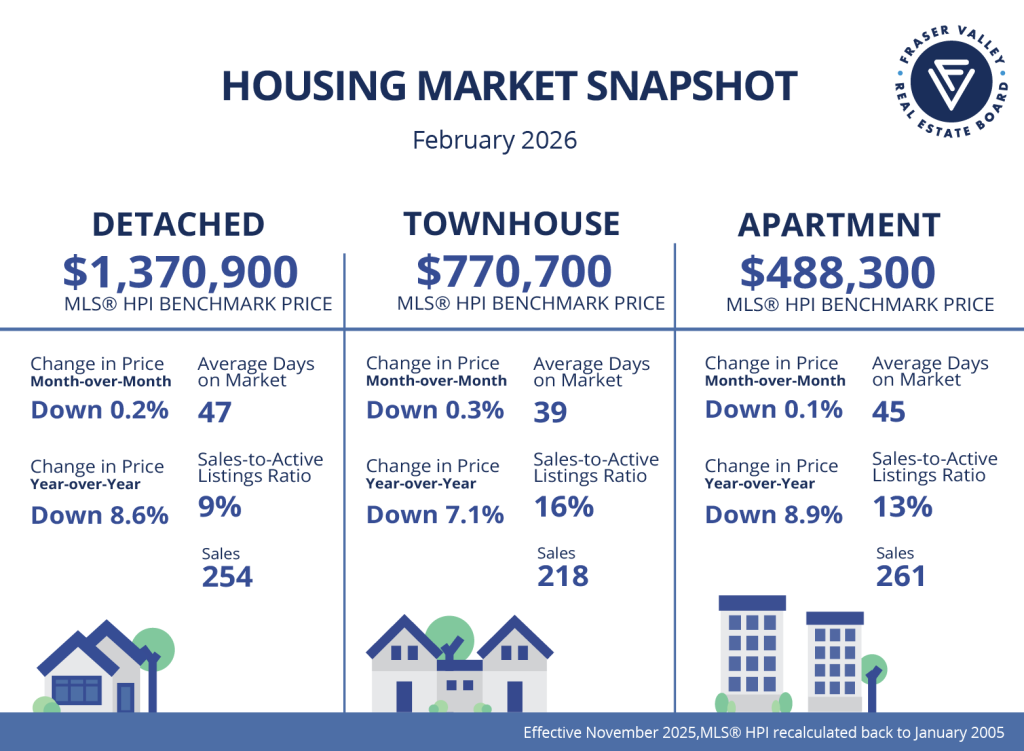
Single family detached homes now sit at $1,370,900, down 0.2% from January and 8.6% compared to February of last year.
The average days on market for active detached listings increased to 42 days, up from 39 days in January. This suggests inventory is continuing to age even as some properties are still finding buyers.
Townhomes
Townhomes declined slightly to $770,700, down 0.3% month over month and 7.1% year over year.
The average days on market increased to 34 days, compared with 32 days in January, again reflecting a market where listings are taking longer to clear overall.
Condos and Apartments
Apartments were effectively flat at $488,300, down 0.1% from January and 8.9% compared to last year.
The average days on market for active condo listings increased to 36 days, up from 33 days in January.
While price declines continue, this represents a significant improvement from the roughly 1% monthly declines seen only a few months ago. The downward trend remains gradual, but those declines are continuing to accumulate.
Time to Sell Improved Slightly
Time to sell improved modestly compared with January.
Average days to sell were:
- 42 days for detached homes
- 34 days for townhomes
- 36 days for condos
Median days to sell were significantly faster:
- Detached homes: 17 days
- Townhomes: 19 days
- Condos: 19 days
That gap between average and median continues to highlight the split market we have been seeing for months.
Well priced homes are still selling relatively quickly. Listings that miss the mark tend to sit and accumulate days on market.
When you compare that with the increasing average days on market, it reinforces a clear point.
Pricing and positioning matter more than ever in this market.
Fast sales are still entirely possible when the property and price align correctly.
Sale to List Price Ratios Remain Stable
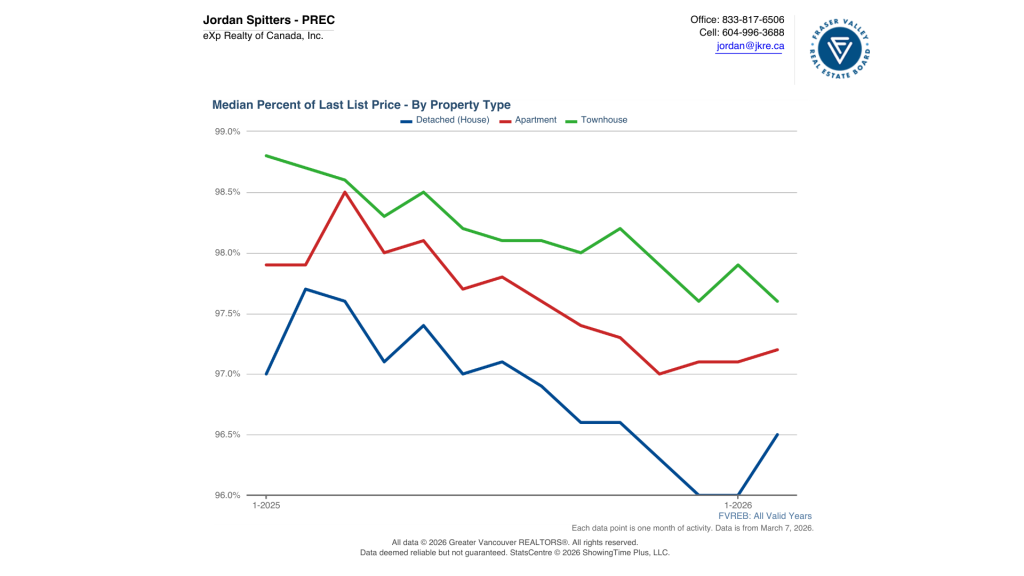
Sale to list price ratios remained relatively steady across property types.
- Detached homes: 96.5% of list price
- Townhomes: 97.6% of list price
- Condos: 97.2% of list price
Buyers are negotiating firmly, but these numbers show that sellers who price realistically are still able to secure deals without dramatic discounts.
What I Am Seeing Locally
Locally, February felt very similar to January.
There are more people out looking. Showings have increased and activity has picked up slightly. However, that increase in activity has not yet translated into a large jump in completed sales.
Many buyers still appear to be waiting for something to trigger a decision.
Subject to sale offers remain common, and negotiation continues to be aggressive. Buyers are evaluating every option available before committing.
At the same time, the conversation around interest rates seems to be stabilizing.
Earlier in the cycle many buyers were sitting on the sidelines waiting for rates to drop. Now most people seem to have come to terms with where rates are today.
Lower rates would certainly help. But in reality the decision to buy is usually driven by a combination of rates and falling prices, rather than one single factor.
Condo Market Showing Early Signs of Activity
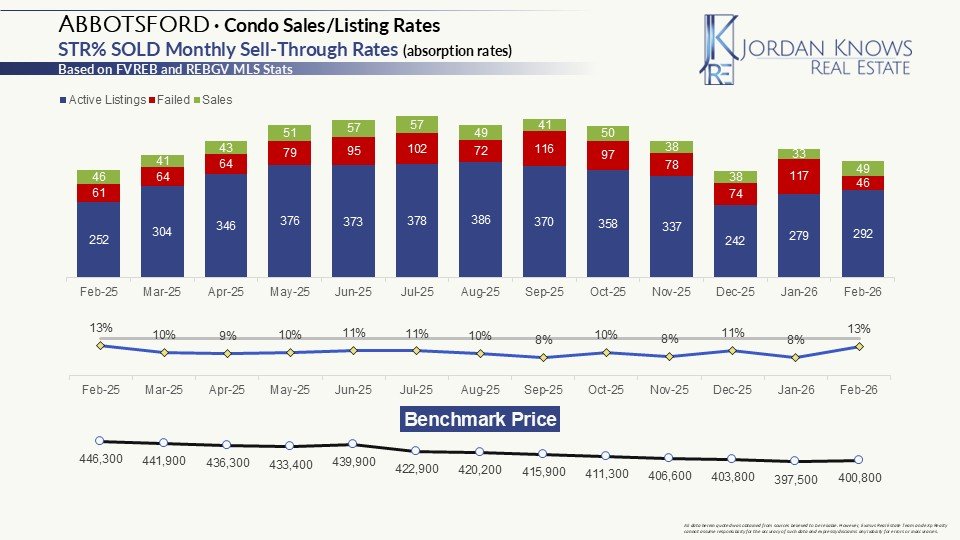
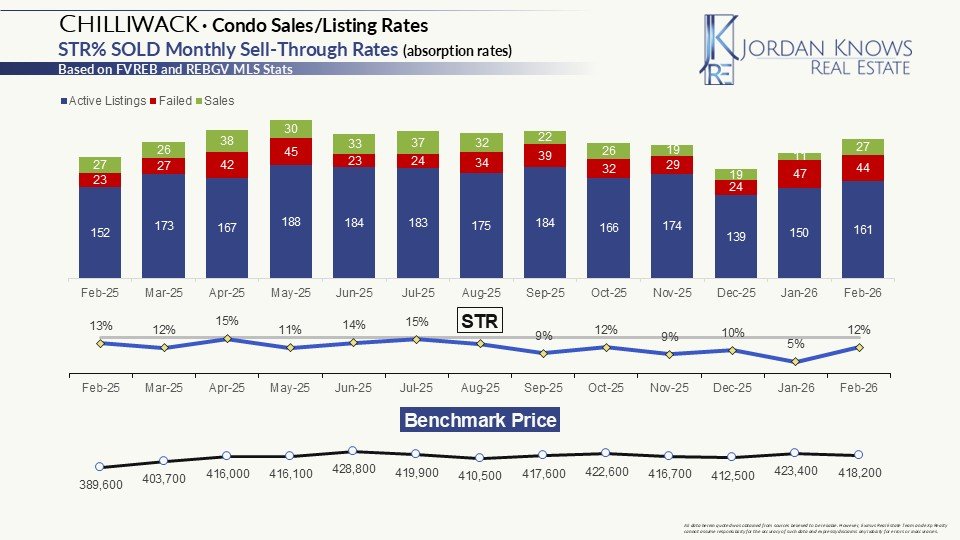
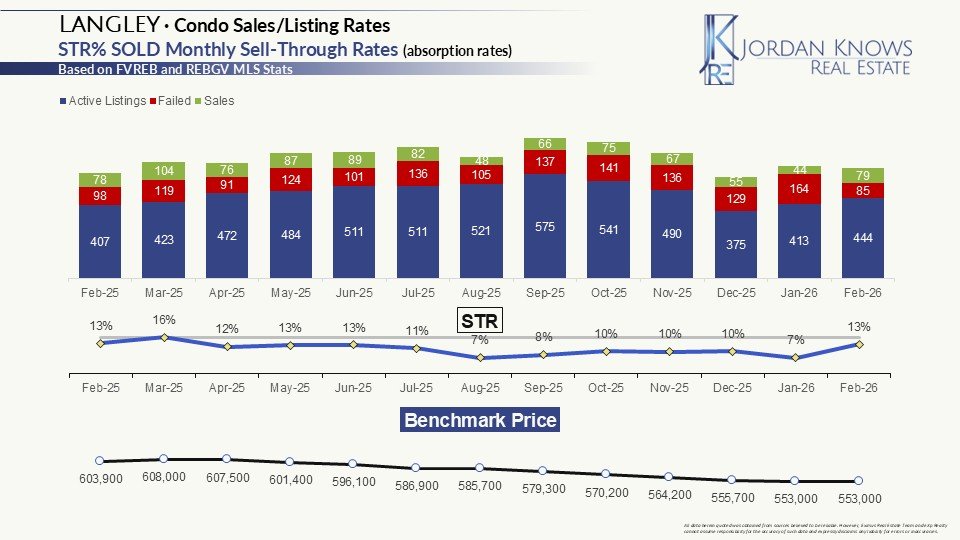
One area that stood out in February was the condo market.
Condos experienced the largest increase in sales, which may signal that first time buyers are beginning to re-enter the market.
If that trend continues it could help unlock movement across the rest of the market as owners begin moving up the property ladder.
That said, it is still early.
Sales improving from the slowest month of the year does not necessarily mean momentum has fully returned, especially when activity remains well below historical averages.
The Broader Economic Picture
The broader economic picture continues to explain much of the hesitation we are seeing.
Canada’s economy has effectively stalled in recent months. Monthly GDP readings through the end of 2025 showed little growth, and per capita GDP has been declining.
This matters because even when the economy is technically growing, the average Canadian is becoming poorer.
That disconnect shows up directly in housing behaviour.
Buyers are cautious.
They negotiate harder.
They are less willing to stretch financially.
The Bank of Canada has reinforced this uncertainty.
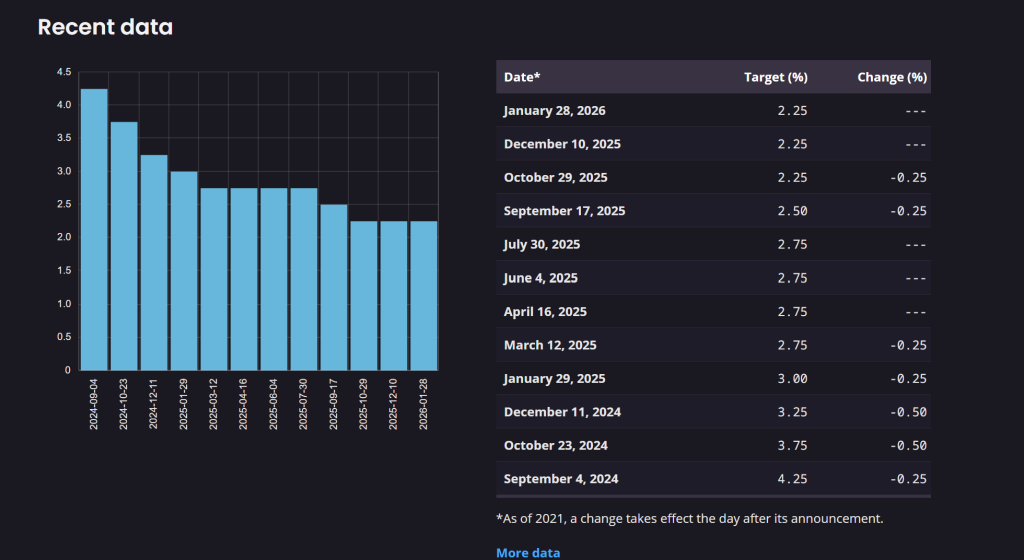
The Bank has now held its policy rate at 2.25% for the second consecutive decision. Governor Macklem has pointed to slowing economic growth, global uncertainty, and the need to confirm that inflation remains under control before making further moves.
For borrowers, this means rate relief is not guaranteed in the near term.
Fixed mortgage rates are also being supported by bond markets.
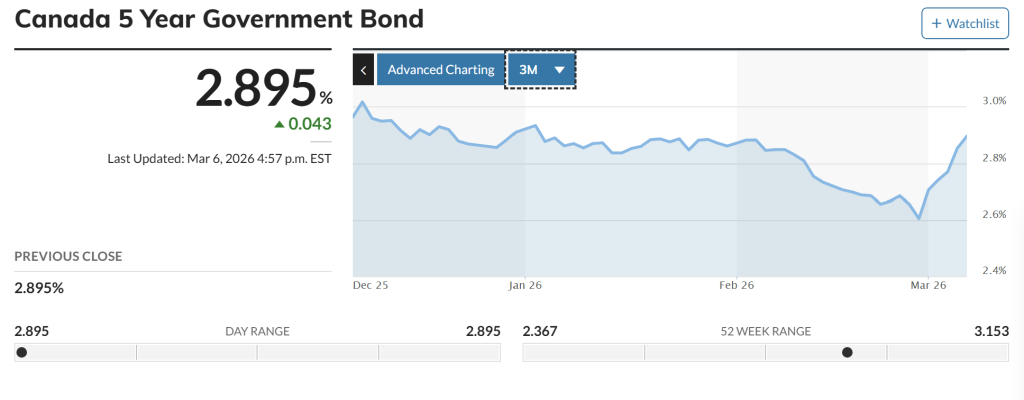
The five year Government of Canada bond yield currently sits around 2.89%. While that is slightly lower than the roughly 3% level seen late last year, it remains elevated enough that fixed mortgage rates are unlikely to fall meaningfully without further declines in bond yields.
The labour market is also sending mixed signals.
Unemployment remains relatively modest overall, but job growth has been uneven and youth unemployment remains elevated. Several recent job reports have leaned toward part time positions while full time employment has been slower to recover.
That combination can affect confidence, particularly for younger households trying to enter the housing market.
The Musqueam Decision and Property Rights Discussion
Another development that could have long term implications for the housing market is the recent Musqueam decision in British Columbia.
The framework established through this decision expands jurisdiction and authority for the Musqueam Nation over a large amount of land and economic activity in the region.
While it does not transfer fee simple ownership in the traditional sense, it introduces another governance layer alongside federal and provincial governments.
In practical terms, this creates a new governing framework tied to ancestry and membership rather than residency or democratic representation within the broader provincial system.
Regardless of where people fall politically on reconciliation, decisions like this raise real questions about property rights, legal certainty, and investor confidence.
British Columbia’s real estate system has historically been built on clear fee simple ownership and predictable legal frameworks.
If those foundations begin to shift or become less certain, it could influence how both domestic and international investors view the stability of property ownership in the province.
Final Thoughts on the Fraser Valley Market
For now, the Fraser Valley market continues to adjust.
Sales are improving slowly from winter lows, but activity remains well below normal levels. Inventory is still elevated, prices continue to edge downward, and buyers remain cautious.
This does not necessarily point to a collapse. However, it does suggest that the path back to a balanced market will likely take time.
For buyers, this remains a market with options and negotiating power.
For sellers, pricing correctly and understanding the competition is more important than it has been in years.
If you would like a deeper breakdown of what is happening in your specific neighbourhood or property type, visit your market area or feel free to reach out directly.
I am always happy to help you make sense of the numbers.


